
Does Insurance Cover Leaks? Auckland Owners Need
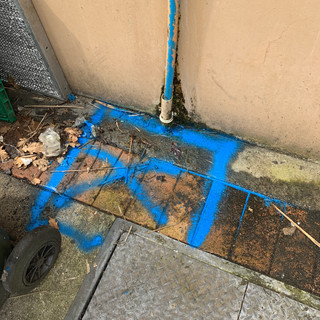
A concealed leak can turn up as a higher water bill, a damp patch beside the skirting board, soft ground near a driveway, or a pool that needs topping up every few days. When repair costs start adding up, the first question is usually: does insurance cover leaks? The practical answer is that it depends on what caused the leak, what has been damaged, and the wording of your policy.
For Auckland property owners, the key distinction is usually between sudden, accidental water damage and a problem that has developed gradually. Insurance may help with the damage caused by a burst pipe, for example, but not always with the cost of replacing the worn pipe itself. Finding the exact source early gives you clearer information for your insurer and can limit further damage while the claim is considered.
Does insurance cover leaks in New Zealand?
Many house, contents and commercial property policies can cover water damage from a sudden and unforeseen event. A pipe that bursts unexpectedly inside a wall, beneath a floor, or in a ceiling space may fall within this category. Damage to linings, flooring, cabinetry, carpets and other insured parts of the property may be considered, subject to your policy limits, exclusions and excess.
However, insurers commonly take a different view where water damage has resulted from gradual deterioration, poor maintenance, corrosion, failed seals, old plumbing, or a leak that has been present for some time. This is particularly relevant to hidden leaks. The leak may not be visible, but an assessor may look for signs such as long-term staining, mould, rot, corrosion or a history of unusually high water use.
The source of the leak and the resulting damage can also be treated differently. Your policy might contribute to repairing damage caused by water escaping from a pipe, while excluding the cost of repairing the faulty pipe, joint, valve or waterproofing membrane that allowed the water to escape. Some policies include limited cover for locating a leak or accessing pipework, while others do not.
There is no single answer that applies to every home, body corporate, commercial building or policy. Read your current wording, including sections covering gradual damage, hidden defects, underground services, water ingress, pipes and drainage. If you are unsure, ask your insurer or broker to explain how the wording applies before approving major repair work.
The cause of the leak matters most
Insurance decisions are generally based on evidence, not just the amount of water lost. A clear diagnosis helps establish whether you are dealing with an isolated failure or an ongoing condition.
Sudden pipe failures
A pipe can split because of a failed fitting, accidental damage, pressure issues or a defect that causes an abrupt failure. If water escapes quickly and damages insured property, there may be a stronger basis for a claim. Acting promptly is still essential. Turn off the water if it is safe to do so, protect belongings from further damage and report the issue to your insurer as soon as possible.
Gradual leaks and deterioration
A small leak beneath a concrete slab or behind a wall can run unnoticed for weeks or months. The eventual visible damage may be significant, but the gradual nature of the problem can affect cover. Some policies provide limited gradual-damage benefits, often with specific caps and conditions. Others exclude it altogether.
This does not mean a hidden leak should be ignored because cover is uncertain. Early detection can reduce water loss, help prevent moisture damage and give you an accurate record of what was found. It also avoids guessing, unnecessary excavation and repairs in the wrong place.
Water ingress and failed waterproofing
Water entering through a basement wall, exterior cladding, shower enclosure, roof penetration or failed membrane is often assessed differently from a burst water pipe. Maintenance-related issues, workmanship concerns and deterioration may be excluded under many policies.
That said, the right testing can separate one issue from another. A damp internal wall may be caused by a plumbing leak, rainwater ingress, a failed shower seal or condensation. The repair approach - and the information your insurer needs - will be different in each case.
What about underground pipes and leaks beneath concrete?
Underground leaks are common sources of uncertainty because the pipe is out of sight and the location is rarely obvious. A leak may be beneath lawn, tarseal, paving, a driveway or a concrete slab. You might only notice water pooling, a drop in pressure, damp ground in dry weather or an unexplained increase in usage.
Whether insurance responds can depend on the pipe type, where it sits, whether it is within your property boundary and the reason it failed. Some policies have specific conditions for underground services or the cost of accessing them. Others may exclude wear and tear or damage to pipes over a certain age.
Before any trenching or concrete cutting is started, it makes sense to locate the problem as accurately as possible. Non-invasive testing can identify the likely leak position and trace pipe runs, reducing the chance of digging up a large area unnecessarily. That can lower reinstatement costs regardless of the insurance outcome.
A professional leak report can support your claim
An insurer may arrange its own assessment, and you should follow its claims process. But an independent leak detection report can provide useful factual information, particularly when the source is concealed or the cause is unclear.
A useful report may record the area tested, the detection methods used, the pipe route where identified, moisture readings, visible evidence of damage and the likely location of the leak. It can also distinguish between a water supply leak, a drainage issue, pool water loss and moisture entering from outside.
At Water Leaks Auckland, our technicians use methods including acoustic listening equipment, trace-wire pipe locating, thermal imaging and moisture testing to investigate difficult leaks without starting with demolition. The goal is straightforward: identify where the water is coming from so repair decisions are based on evidence.
A detection report does not guarantee that a claim will be accepted. Insurers make that decision under the terms of the policy. It can, however, help you explain the problem clearly, obtain repair quotes for the correct area and show that reasonable steps were taken to investigate and limit damage.
What to do when you find or suspect a leak
Your first priority is preventing further loss. If you have a burst or active internal leak, isolate the water supply where possible and arrange urgent plumbing assistance. Move furniture, lift wet items off the floor and photograph affected areas before extensive clean-up, provided it is safe to do so.
For a suspected concealed leak, record your water metre reading and any changes in water use, pressure, dampness or pool level. Take photographs of visible symptoms and keep invoices, reports and correspondence. Contact your insurer before authorising large repairs, especially work involving walls, floors, concrete or landscaping. Emergency work to make the property safe may be necessary, but keep the scope limited until you have direction where practical.
Do not assume that a plumber or leak detection specialist can confirm cover. They can diagnose the physical issue and recommend repairs. Your insurer determines whether the event, damage and costs fall within your policy.
Questions worth asking your insurer
When you speak with your insurer, be specific. Ask whether the policy covers the resulting water damage, the cost of finding the leak, access to concealed pipework, repair of the failed pipe and reinstatement of surfaces such as flooring, concrete, landscaping or cabinetry. Also ask about your excess, any gradual-damage limit and whether the insurer needs to approve contractors before work begins.
For commercial properties, clarify business interruption implications as well. A leak affecting a tenancy, kitchen, plant room, pool facility or customer area can create costs beyond the physical repair. Early testing gives facilities teams a firmer basis for planning access, repairs and temporary controls.
A leak is stressful enough without paying for exploratory work that does not solve the problem. Get the source located accurately, protect the property from further damage, and give your insurer clear facts to work with. Even where cover is limited, a targeted repair is usually a far better outcome than opening walls, cutting concrete or excavating blindly.


Comments